Hunting Bows Market Overview and Industry Significance
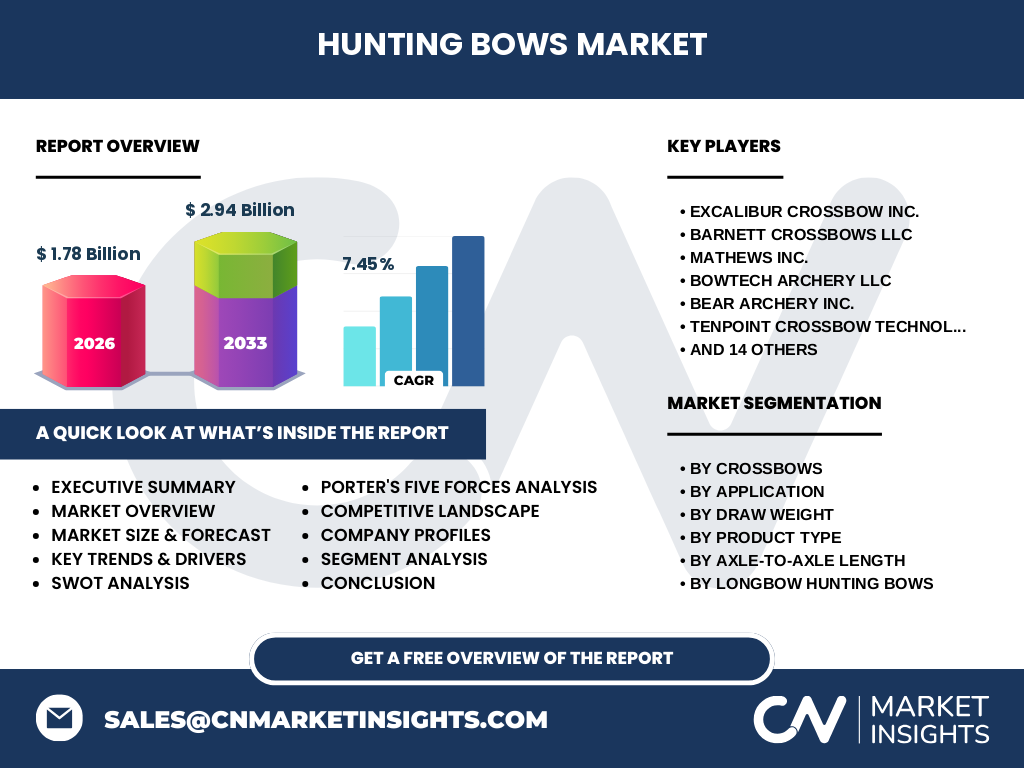
Our analysis indicates that the Hunting Bows Market represents a vital segment of outdoor sporting goods, valued at 1.78 Billion in 2026. This sector encompasses precision-engineered compound bows, recurves, longbows, and advanced crossbows utilized for big game hunting, bow fishing, and wildlife management under strict state wildlife agency regulations.
Structural Growth Drivers and Market Restraints
The market is propelled by a 7.45% CAGR driven by technological innovations in carbon-reinforced materials and high-velocity designs from manufacturers like TenPoint Crossbow Technologies Inc. and Mathews Inc. However, supply chain bottlenecks for aerospace-grade aluminum and stringent cross-border export tariffs on precision archery equipment serve as notable operational restraints.
The Shift Toward Advanced Carbon and High-Velocity Systems
Industry trends reveal a pronounced migration toward lightweight, carbon-reinforced longbows and reverse-draw crossbows. Companies such as Ravin Crossbows LLC leverage this shift to deliver compact, high-velocity hunting solutions that cater to modern hunters seeking maximum kinetic energy and maneuverability in dense woodland terrain.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic catalyzed a surge in outdoor recreation, temporarily disrupting raw material logistics for timber and resin but ultimately accelerating direct-to-consumer digital adoption. Established firms like Bear Archery Inc. and Bowtech Archery LLC successfully navigated these supply disruptions, cementing a robust post-pandemic recovery trajectory.
Competitive Benchmarking and Market Concentration
The competitive landscape is moderately consolidated, featuring aggressive IP litigation over cam systems and trigger mechanisms. Industry heavyweights like Hoyt Archery Inc. and Excalibur Crossbow Inc. maintain dominant market share through proprietary hybrid-cam designs and precision engineering, leaving niche players to compete on custom handcrafted wood aesthetics.
Executive Summary of the Hunting Bows Market
Our research underscores a thriving commercial landscape for hunting bows, projected to expand from 1.78 Billion in 2026 to reach 2.94 Billion by 2033. Strategic investments in binary-cam compound systems and lightweight takedown recurves will dictate market leadership over the forecast window.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric models, the Hunting Bows Market industry trends point toward sustained expansion at a 7.45% CAGR, pushing total valuation to 2.94 Billion by 2033. This growth is heavily underwritten by rising participation rates among professional hunters and technological upgrades in medium draw weight configurations.
Segmentation Analysis by Product Type, Application, and Draw Weight
The market breaks down across several critical vectors: Product Type (Compound, Recurve, Longbow, Crossbows), Application (Big Game, Small Game, Bowhunting, Bow fishing), and Draw Weight (Low, Medium 50-70 lbs, High Above 70 lbs). Each segment addresses specialized regulatory frameworks and hunter demographics, from AMS Bowfishing Inc. in specialized aquatic niches to Elite Archery Inc. in professional big game pursuits.
Regional Market Analysis and Geographic Distribution
North America dominates global consumption due to extensive state-managed hunting tags and robust distribution networks utilized by Darton Archery Inc. and Mission Archery LLC. Meanwhile, Europe and the Asia-Pacific region exhibit emerging growth driven by traditional archery clubs and expanding distribution partnerships by Samick Sports Co. Ltd. and Win&Win Archery Co. Ltd.
In-Depth Regional Review of North American and European Markets
North America remains the epicenter of high-value compound bow adoption, supported by favorable state game laws and widespread bowhunting seasons. Conversely, the European market prioritizes traditional recurve and reflex-deflex longbows due to strict regional firearm restrictions, creating localized demand pockets for specialized manufacturers.
Strategic Company Profiles and Market Positioning
Leading industry participants occupy distinct strategic niches: Mathews Inc. focuses on vibration-dampening bow technology, Barnett Crossbows LLC targets high-performance value, and Gearhead Archery LLC pioneers ultra-compact tactical designs. These distinct positioning strategies enable firms to capture specific consumer segments effectively.
Porter's Five Forces Analysis of the Archery Sector
Porter's analysis reveals moderate-to-high supplier power due to proprietary composite material patents, balanced by intense rivalry among established brands like Prime Archery LLC and Xpedition Archery LLC. Threat of substitutes remains low given the regulatory preference for traditional hunting implements over modern firearms in specific jurisdictions.
SWOT Analysis of the Hunting Bows Market
Key strengths include advanced engineering and loyal consumer demographics; weaknesses involve high initial R&D costs for carbon fiber tooling. Opportunities lie in expanding digital retail channels, while threats include shifting wildlife conservation policies and potential import tariffs on raw fiberglass and resin components.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction—such as carbon fiber, aircraft-grade aluminum, and laminated hardwoods—moving through precision CNC machining at facilities operated by innovators like Obsession Bows LLC, and culminating in distribution via specialized outdoor outfitters and e-commerce platforms.
Investment Insights and High-Potential Growth Areas
Investors should direct capital toward companies specializing in lightweight, carbon-reinforced longbows and binary-cam compound bows. Brands integrating IoT-enabled tuning accessories and advanced vibration dampening represent prime acquisition targets for private equity firms entering the outdoor sports sector.
Conclusion and Key Takeaways for Industry Stakeholders
The Hunting Bows Market market size expansion to 2.94 Billion by 2033 underscores the sector's resilience and profitability. Stakeholders must prioritize material innovation and digital marketing to capture market share in both traditional recurve and high-velocity crossbow categories.
Research Methodology and Baseline Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-suite executives at firms like Martin Archery Inc. and Ten Ring Archery LLC, and secondary macroeconomic indicators regarding outdoor recreation expenditure and state hunting license issuance.
Scope of the Report and Analytical Limitations
This comprehensive report evaluates the global Hunting Bows Market analysis across specified product lines, draw weights, and end-user experience levels from 2026 to 2033. Limitations include unforeseen regulatory shifts in state game management policies and macroeconomic currency fluctuations affecting international trade.
Recent Developments, Product Launches, and Strategic Partnerships
Recent industry momentum features aggressive product rollouts, including high-velocity compact crossbows by Ravin Crossbows LLC and strategic distribution agreements forged by Bear Archery Inc. These corporate maneuvers highlight an industry-wide commitment to enhancing kinetic performance and expanding global retail footprints.